Every personal finance article says to save three to six months of expenses. Almost none of them tell you which number to pick or why. The Federal Reserve’s 2023 survey found that 37 percent of American adults could not cover an unexpected $400 expense with cash or savings-account equivalents. The emergency fund gap is real, and vague guidance makes it worse. This guide replaces the range with specific targets based on your income, household, and risk profile.
For a broader look at saving strategies, see our pillar guide on saving money on a tight budget.
Why is the three-to-six-months rule not specific enough?
The range exists because financial planners need a general answer that works across audiences. But “three months” for a dual-income household with stable government jobs is very different from “three months” for a single freelancer with seasonal income. The variables that matter are income stability, household structure, fixed obligations, and insurance coverage.
A single person renting an apartment with a stable W-2 job and health insurance through work faces limited financial risk from a job loss. Unemployment benefits cover 40 to 50 percent of prior wages in most states, and the job search typically takes 2 to 4 months. Three months of essential expenses is adequate. A self-employed homeowner with a family and high-deductible health plan faces compounding risks: no unemployment benefits, a mortgage that cannot flex, and healthcare costs that can spike to $1,500 per month on COBRA. That person needs 9 to 12 months.
How much emergency fund do you actually need?
The table below provides specific targets based on situation. “Essential expenses” means rent or mortgage, utilities, groceries, insurance premiums, minimum debt payments, and transportation. Not dining out, subscriptions, or discretionary spending.
| Situation | Monthly Essentials | Months Needed | Target Fund | Reasoning |
|---|---|---|---|---|
| Single, renter, stable W-2 job | $2,200 | 3 | $6,600 | Unemployment benefits + short job search window |
| Single, renter, freelancer/gig | $2,200 | 6 | $13,200 | No unemployment benefits, variable income gaps |
| Couple, dual income, renting | $3,500 | 3 | $10,500 | Second income provides built-in buffer |
| Couple, single income, renting | $3,500 | 6 | $21,000 | Full household depends on one paycheck |
| Family, homeowner, stable jobs | $4,500 | 6 | $27,000 | Mortgage cannot flex, home repairs are unpredictable |
| Family, homeowner, one freelancer | $4,500 | 9 | $40,500 | Combined income instability + homeowner risk |
| Self-employed, homeowner, family | $4,500 | 9-12 | $40,500-$54,000 | Maximum income risk, no safety net |
These numbers assume the emergency fund covers only essential expenses. If your monthly essentials are lower or higher, adjust proportionally. The number of months is what matters, not the dollar figure in isolation.
Where should you keep your emergency fund?
The emergency fund must be liquid, FDIC-insured, and earning some interest. It should not be in the stock market, locked in a CD, or mixed with your checking account where you might spend it.
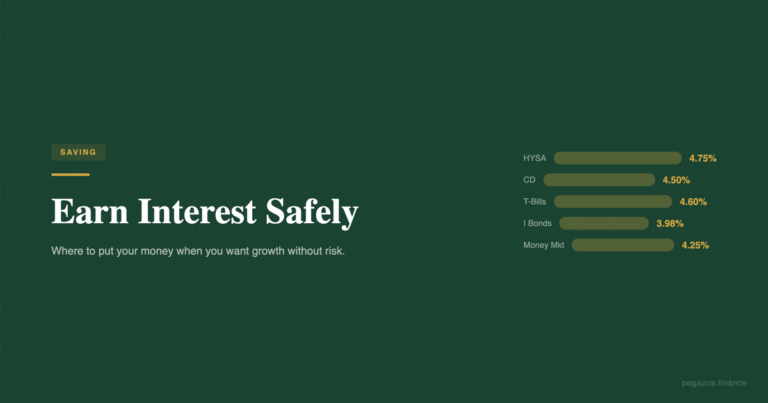
A high-yield savings account (HYSA) at an online bank is the best option for most people. As of late 2026, the top HYSAs from Marcus by Goldman Sachs, Ally Bank, and Capital One 360 offer rates between 4.00 and 4.50 percent APY with no minimum balance and next-business-day transfers. That means a $20,000 emergency fund earns roughly $800 to $900 per year in interest while staying fully accessible.
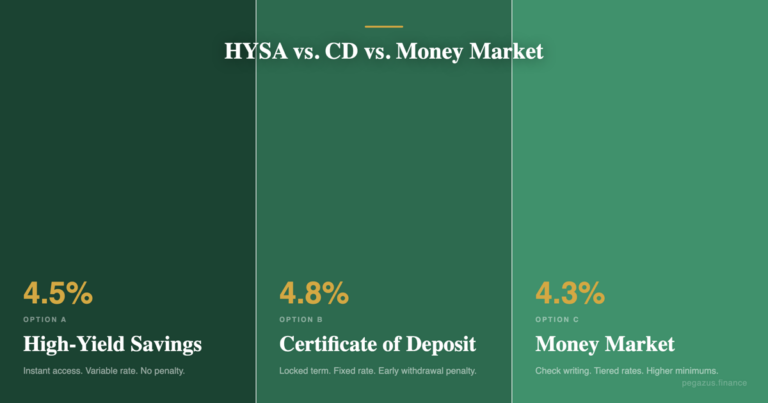
Keep the emergency fund at a different bank than your primary checking account. The friction of a 1-to-2 business day transfer is intentional. It prevents impulsive spending while keeping the money reachable within 48 hours. For a detailed comparison of where to park your savings, read our guide on HYSA vs. CD vs. money market accounts.
How do you build an emergency fund starting from zero?
Building a five-figure emergency fund on a median income feels impossible at the start. The key is to break it into milestones and automate the process so it does not depend on willpower.
Milestone 1: $500. This covers a minor car repair or urgent medical copay. Reach it within 30 to 60 days by redirecting one recurring expense (cancel a subscription, pack lunches for a month, pause a gym membership). The CFPB recommends starting with small automatic transfers as low as $10 per week.
Milestone 2: $1,000. This is the minimum buffer that prevents most common emergencies from going on a credit card. At $25 per week automated from checking to your HYSA, you reach $1,000 in 40 weeks. At $50 per week, 20 weeks.
Milestone 3: One month of essentials. This is where the fund starts working as real insurance. Boost contributions by directing any one-time money here: tax refunds, side income, cash gifts, rebates. The America Saves program reports that people who set a specific savings goal are twice as likely to reach it.
Milestone 4: Full target. Once one month is banked, increase the automated weekly transfer by $5 to $10 each quarter. Lifestyle inflation is the biggest threat at this stage. When you get a raise, direct at least half the after-tax increase to the emergency fund before adjusting your budget upward.
Should you automate emergency fund contributions or save manually?
Automate. This is not a close call. Research from the National Bureau of Economic Research shows that automatic enrollment and automatic escalation increase retirement savings rates by 50 to 100 percent compared to voluntary participation. The same behavioral principle applies to emergency savings. Money you never see in your checking account does not get spent.
Set up a recurring transfer from your checking account to your HYSA on the day after your primary paycheck deposits. If you are paid biweekly, set two transfers per month. Start with an amount that feels almost too small to matter, then increase it by $10 every two months. In 12 months, you will have built a meaningful balance without ever feeling a sharp budget cut.
For broader investing context alongside your emergency fund, see our investing guide for beginners. Our research methodology explains how we verify savings rates and financial data.